One person who sees
your whole financial picture.

Many families have a tax preparer who files the return in April and an adviser who manages the money — and nobody looking at both together. I do both, all year, for a small number of families.

Book a free consultation Free, 30–45 minutes. In person, by video, or by phone. Nothing to decide on the call.
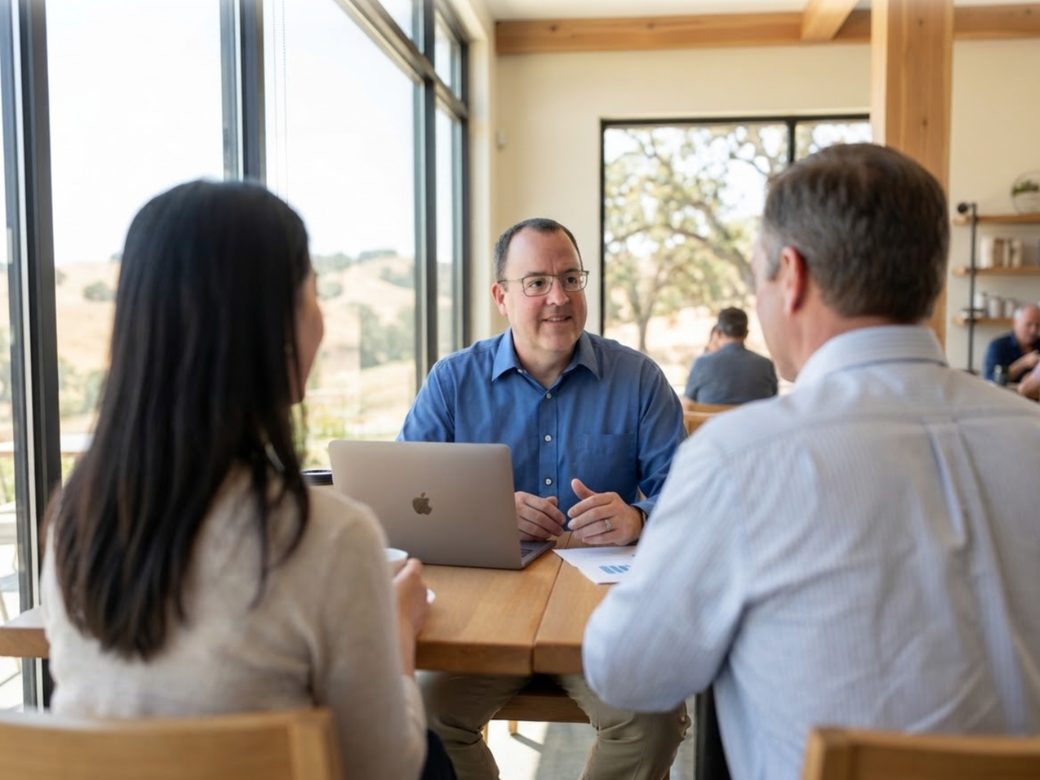
Eric talking with two people across a sunlit table, a laptop and printed charts between them.
Fee-only fiduciary Tax professional — full IRS representation rights Registered investment adviser in California Walnut Creek — and I'll come to you

Your taxes and your investments,
handled by one person.

Four things that only work when the same person does both.

Tax moves get made before April, not after.

Roth conversions sized against the bracket you're actually in. A concentrated position sold across two tax years instead of one. Giving that also satisfies a withdrawal you have to take anyway. By the time most people sit down with a preparer, those decisions have already been made for them.

IRS letters come to me instead of you.

I'm licensed to represent you before the IRS. With one form on file, official correspondence arrives at my desk and I answer it — rather than sitting unopened on a kitchen counter while someone works out who to call.

One investment strategy across every account.

Losses harvested when markets dip. The right holdings in the right accounts. Every investment move made with your tax return already in view, instead of two professionals optimizing separately and neither seeing the other's work.

You call me directly, and I answer.

An offer on a house. A form you don't recognize. A decision you'd like a second opinion on before you make it. That's exactly when I want to hear from you, and it isn't billed on top.

Where are you right now?

Money and Retirement

Your own situation has got complicated.

You're in your 40s, 50s or 60s, you earn well, and your financial life has more moving parts than it used to.

  • Equity compensation you've never fully understood
  • A concentrated position you're nervous about selling
  • Rental property, K‑1s, a return that spans two states
  • A plan to stop working before 59½ — and questions about reaching your own money
  • The window between retiring and required withdrawals, which is where most of the tax savings live

Money and Aging

You're getting affairs in order — yours, or a parent's.

Either you're doing this for yourselves, or you're the adult child who has become the one handling it. Both are welcome here.

  • Beneficiary forms nobody has looked at in 30 years
  • Accounts scattered across former employers, and no single picture of any of it
  • Required withdrawals, Medicare premiums, the step‑up in basis
  • One spouse has always handled the money and the other hasn't needed to
  • A spouse has died, and there's a list of things with real money and real deadlines attached
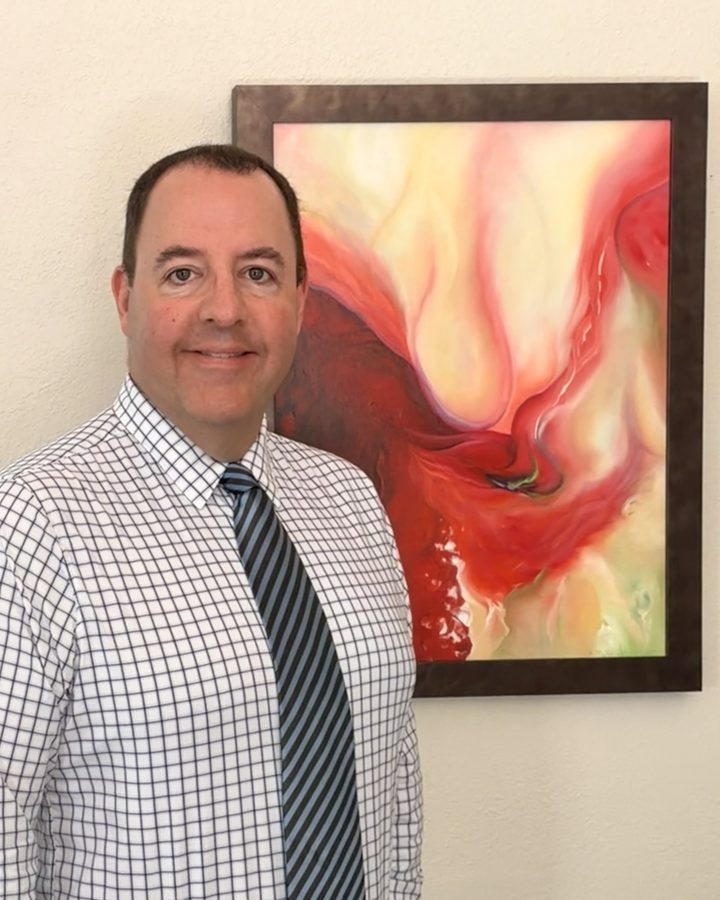
Eric Etu

Hi, I'm Eric.

I've spent 20 years reading families' financial paperwork — tax returns, pay stubs, K‑1s, bank statements. Some of it preparing returns for low-income families here in the Bay Area, which I've done every season since 2014. Some of it building the software that banks and lenders use to do the same reading at scale.

What I kept noticing was that nobody was looking at the whole picture. A family makes a perfectly sound investment decision and gets a surprise tax bill in the same year. Nobody did anything wrong — the two halves were just sitting in different offices.

So I built the practice I'd want for my own family. I'm a fiduciary investment adviser and a tax professional, I take on a small number of households, and I do the work for each of them myself. If you're near Walnut Creek, I'll come to you.

Get to know me

Let's talk. It's free.

A short conversation about what you've got going on — your taxes, your investments, or helping a parent with theirs. No pitch, no paperwork, no obligation.

Book a free consultation
30–45 minutes In person, by video, or by phone Nothing to bring